
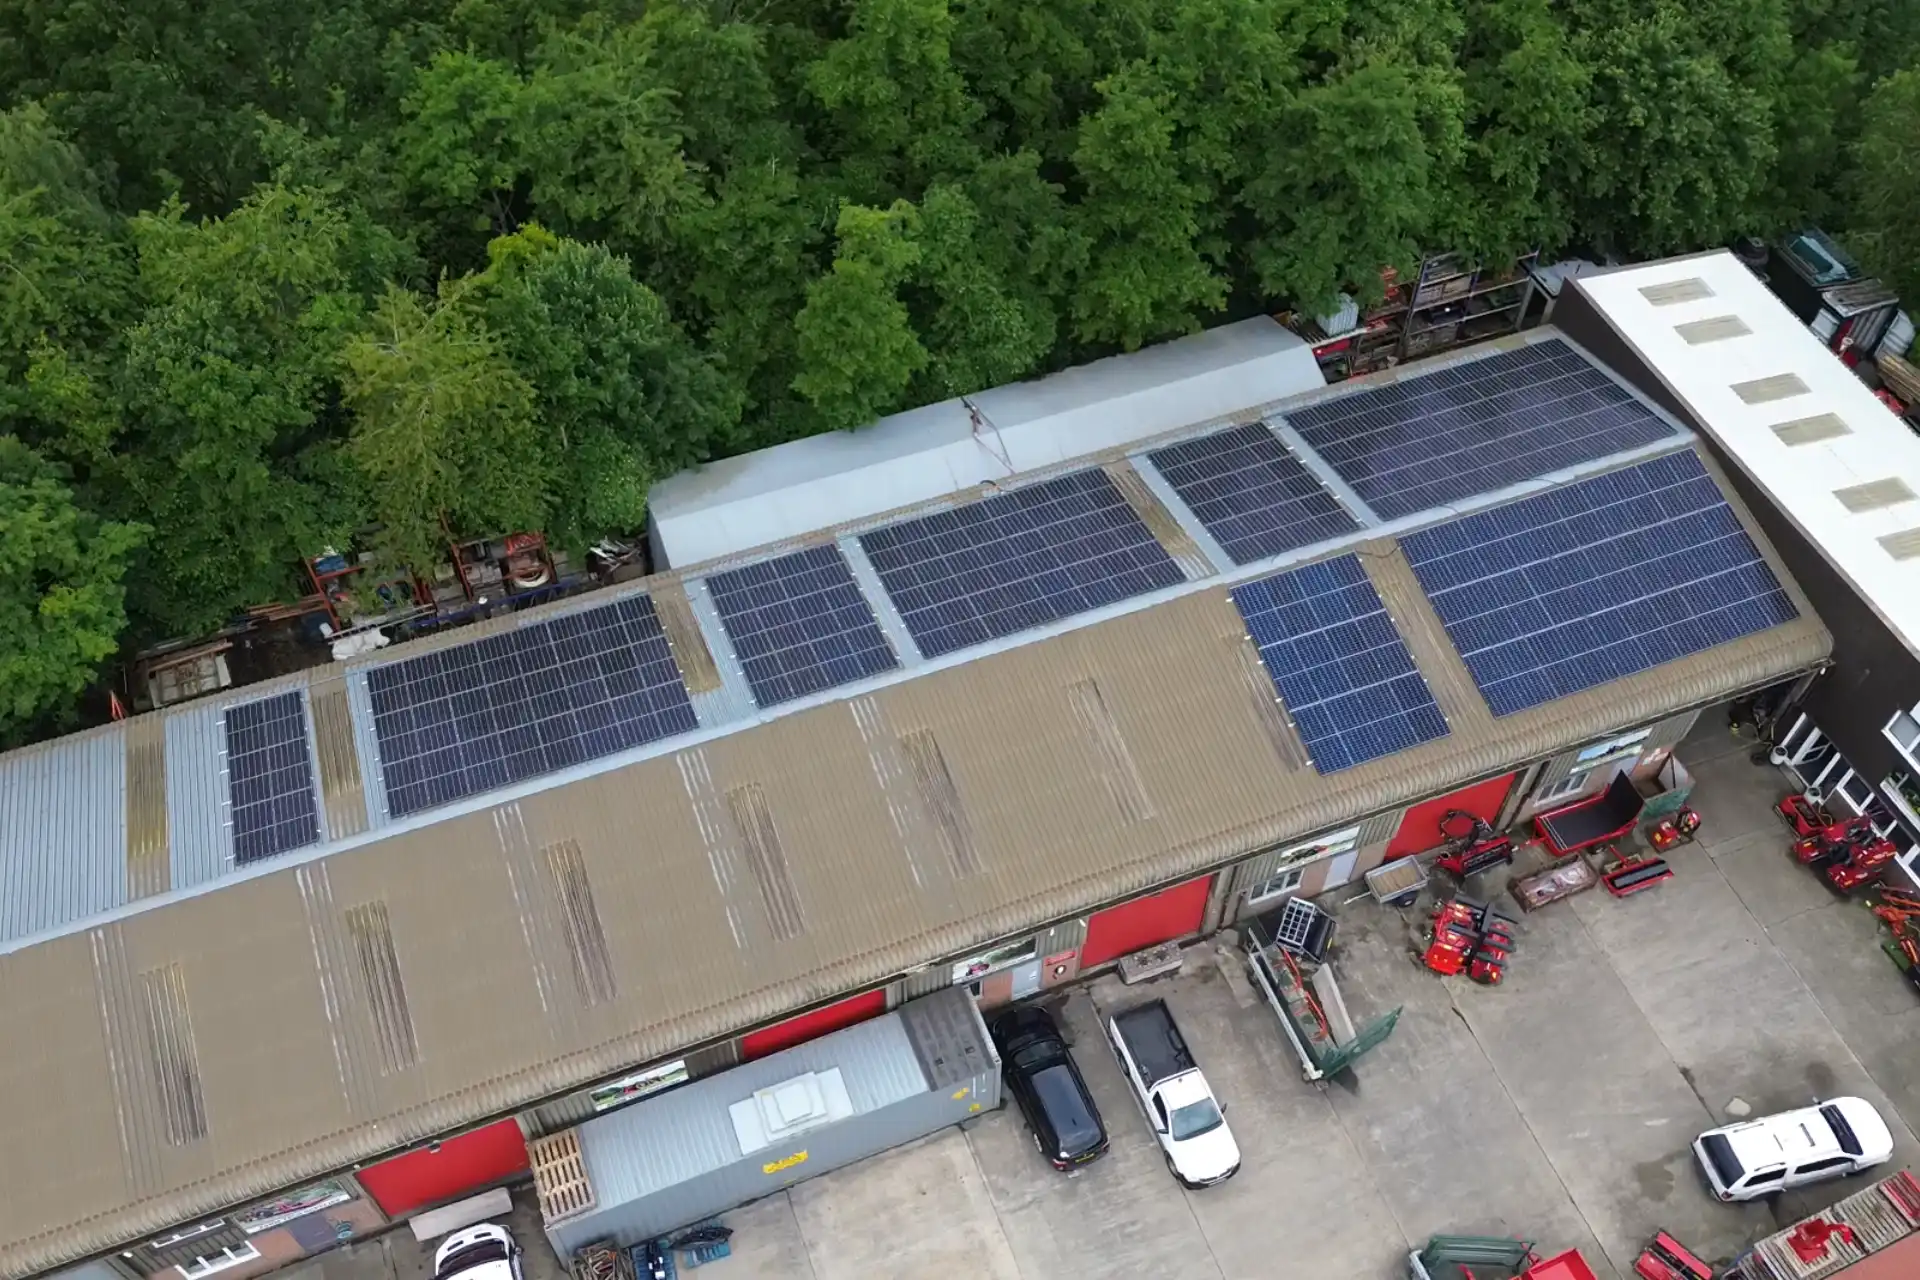
Funding commercial solar panels in Scotland: capital allowances, VAT, PPA and finance
Written for finance directors, business owners and farm managers in Scotland weighing up solar PV and battery storage: how capital allowances on solar panels work, what VAT you pay, and which funding routes and grants are open, checked on 15 October 2026.
For tax, solar panels count as special-rate plant and machinery. A business that buys a system can usually claim the Annual Investment Allowance, deducting 100% of the cost from profits before tax on up to £1 million of spend a year. Companies can claim a 50% first-year allowance on special-rate spend beyond that, with the balance written down at 6% a year. Full expensing does not cover solar. VAT on business premises is 20%, normally reclaimable if you are VAT-registered. A solar PPA removes the upfront cost and asset finance spreads it, and there is no general Scottish grant for business solar.
Funding routes for business solar at a glance
Solar panels for a business in Scotland can be paid for in four main ways: buying outright, hire purchase, leasing or a solar PPA. The choice settles more than cash flow, because it decides who owns the system, who claims the tax relief and who keeps the income from exported power.
Export income and the few grants that exist sit on top of whichever route you choose. Still deciding what to install first? Our commercial renewable energy page covers solar, storage and EV charging together.
| Route | Who owns the system | Upfront cost | Who claims capital allowances | Who gets export income |
|---|---|---|---|---|
| Buy outright | Your business | The full cost, plus VAT | Your business | Your business |
| Hire purchase | Your business, treated as owner for tax | Spread over the agreement | Your business, normally through the fixtures rules | Your business |
| Finance or operating lease | The leasing company | Spread as rentals | The leasing company, unless it is a long funding lease | As set in the lease |
| Solar PPA | The PPA funder | None for the system | The funder | As set in the PPA |
Capital allowances on solar panels: how the relief works
Capital allowances let a business deduct spending on plant and machinery from its taxable profits. Since April 2012, all capital expenditure on providing solar panels has been special-rate expenditure under section 104A(1)(g) of the Capital Allowances Act 2001, and that label decides which allowances you can use. The rules below are correct as of 15 October 2026.
- Annual Investment Allowance (AIA). Deducts the full cost of qualifying plant from profits before tax, on up to £1 million of spend a year. Two or more companies controlled by the same person share one AIA, and a shorter accounting period gets a proportionally smaller limit.
- 50% first-year allowance. A company within the charge to corporation tax can deduct 50% of special-rate spend on new, unused plant in the year it is incurred, then add the balance to the special rate pool in the following accounting period. It did not end in March 2026: the Finance Act 2024 removed the cut-off, so it is permanent.
- Writing-down allowance. Anything left in the special rate pool is relieved at 6% a year on the reducing balance.
Why full expensing does not apply. Full expensing is a 100% first-year allowance for main-rate plant, and HMRC states that companies cannot claim it for special-rate assets such as solar panels. The 40% first-year allowance for spend from 1 January 2026 is limited to main-rate plant too, and Enhanced Capital Allowances, still quoted on some websites, ended in April 2020.
Sole traders, partnerships and farms. Unincorporated businesses using traditional accounting use the AIA. On the cash basis, the standard method for sole traders and partnerships, capital allowances cover only business cars, so ask your accountant which method suits you. The 50% allowance is for companies only, so their spend beyond the AIA goes into the 6% pool. A partnership can claim the AIA only if all its members are individuals, which rules out a farm partnership with a company as a partner. If you are a Scottish taxpayer, the allowance comes off profits taxed at Scottish income tax rates, which run from 19% to 48% in 2026 to 2027, so its cash value depends on your band. You cannot claim the full value of a system you also use outside the business.
- Batteries. HMRC's special-rate rule names solar panels and says nothing about battery storage, so agree how a battery is treated with your accountant before relying on a rate.
- EV chargepoints. These have their own 100% first-year allowance for new, unused equipment, until 31 March 2027 for companies and 5 April 2027 for income tax. Any part of a cost met by a public grant, such as the Workplace Charging Scheme, generally does not qualify.
- Timing. Spend counts when there is an unconditional obligation to pay, or on the due date if that is more than four months later, so a project near your year-end can move the claim by a year.
- Selling later. Selling the system after claiming may mean tax to pay through a balancing charge.
The table below is a hypothetical example, not a quote or a real project: a company taxed at the 25% main rate of corporation tax spends £100,000 on a rooftop array. Companies with profits of £50,000 or less pay 19%, with marginal relief between £50,000 and £250,000, so the cash value moves with your rate. Capital-allowance treatment depends on your structure, so take your own tax advice; we will give your accountant the figures.
| Hypothetical: £100,000 spend, 25% tax rate | AIA available | AIA already used: 50% first-year allowance |
|---|---|---|
| Allowance in year one | £100,000 × 100% = £100,000 | £100,000 × 50% = £50,000 |
| Tax saved in year one | £100,000 × 25% = £25,000 | £50,000 × 25% = £12,500 |
| Added to the special rate pool | Nothing | £50,000, in the following period |
| Year two writing-down allowance | Nothing | £50,000 × 6% = £3,000, saving £750 |
| Year three writing-down allowance | Nothing | £47,000 × 6% = £2,820, saving £705 |
VAT on commercial solar and battery storage
Solar panels and batteries installed on business premises are standard-rated, so the invoice carries 20% VAT. The 0% rate in HMRC's VAT Notice 708/6 applies only to residential accommodation and, from 1 February 2024, to buildings intended for use solely for a relevant charitable purpose: broadly a charity's non-business use, or a village hall or similar community facility. That rate runs until 31 March 2027 and reverts to 5% from 1 April 2027 (correct as of 15 October 2026). Hotels, inns and similar establishments are standard-rated, even though people stay in them.
If you are VAT-registered, you reclaim VAT on items bought for use in your business through your VAT return. Two limits apply: where the system is also used privately you can only reclaim the business proportion, and you cannot reclaim VAT on purchases used to make VAT-exempt supplies. Compare quotes ex-VAT, and plan for paying the VAT before you get it back.
Export income: the Smart Export Guarantee for businesses
The Smart Export Guarantee (SEG) pays for the electricity you export, and it is not limited to households: it covers solar PV installations up to 5 MW of total installed capacity in Great Britain. Under Ofgem's guidance for generators, correct as of 15 October 2026:
- Systems up to 50 kW must show that the installation and the installer are suitably certified, for example with an MCS certificate or an equivalent standard.
- Systems above 50 kW and up to 5 MW need installation certification but not installer certification, and each SEG licensee decides what evidence it accepts.
- You need an export meter that takes half-hourly readings and an export MPAN.
- Suppliers with at least 150,000 domestic customers must offer a SEG tariff, and others may choose to. Your SEG licensee does not have to be your import supplier, and rates must always be above zero.
Set export income against what a unit is worth on site. Ofgem's latest SEG annual report found that untied tariffs, which are open to any eligible generator, averaged 4.39p/kWh in the year to 31 March 2025, while DESNZ puts the average non-domestic electricity price at 24.51p/kWh, including the Climate Change Levy, for April to June 2026. On those averages a kilowatt-hour used on site is worth several times one exported, which is why we size business systems around self-consumption first and look at storage for any surplus.
Export payments a business receives are normally business income: HMRC's manual says so for the Feed-in Tariff export payments that came before the SEG, so ask your accountant how yours are taxed. Ecoaim is MCS-certified for solar PV and battery storage, the certification Ofgem's guidance names for systems up to 50 kW.
Solar PPA: commercial solar with no capital outlay
Under an on-site solar PPA, a funder pays for and owns a system installed on your roof or land, and you buy the electricity it generates at an agreed unit rate. There is no capital outlay for the system. Because capital allowances go to the legal owner of an asset, the funder claims them, not you.
That makes a PPA a good fit where allowances are worth little to you, such as a charity, a public body or a company that will not pay much tax for a while, or where you would rather keep capital for core operations. The trade-off is that you give up the allowances and part of the long-term saving, and who keeps the export income is down to the contract. For terms, unit rates and buy-out options, read how PPA funding works.
Business grants for solar panels in Scotland: what is open now
Here is the position when we checked on 15 October 2026: we found no government grant open to Scottish businesses in general for installing solar PV. What does exist:
- Business Energy Scotland SME Loan Scheme. Business Energy Scotland is funded by the Scottish Government and managed by Energy Saving Trust, and its advice is free and impartial. Its SME Loan offers interest-free loans of £1,000 to £100,000, with up to £130,000 in total across loans and cashback, and an 8-year repayment term, to small and medium-sized businesses based in Scotland that have traded for at least 12 months. The scheme is not accepting new applications for solar PV projects, and its cashback is not available for batteries. It still funds energy-efficiency work such as lighting, insulation and controls, with cashback of 75% of eligible costs up to £20,000, first come, first served.
- Home Energy Scotland. Its grant and loan are for homeowners, so a business cannot use them for solar panels or batteries.
- Workplace Charging Scheme. OZEV's Workplace Charging Scheme gives up to £500 per socket for installations completed from 1 April 2026, capped at 75% of costs including VAT, with a limit of 40 sockets in total across your sites. It is open in Scotland until 31 March 2027. Chargers at a business are for staff and fleet use, though charities and small accommodation businesses can let anyone use them. The site needs dedicated off-road parking, and an OZEV-authorised installer claims the grant and deducts it from your invoice.
- Farms. Scotland's Future Farming Investment Scheme listed solar panels among the renewable energy investments that were not eligible in its 2025 round. A new round of up to £20,000 per business is due to open in winter 2026, with its eligible-items list still to be published, so check it when it appears. See solar for farms for the wider agricultural picture.
- Local support. Business Gateway provides free, publicly funded business support across Scotland, and the Find Business Support service, delivered by Scottish Enterprise and partners, lists public grants and funding. Both are worth checking for local schemes.
Asset finance, hire purchase and leasing: who claims what
Asset finance spreads the cost, but each structure treats capital allowances differently. We do not lend, but we will give your lender and accountant the system figures they need.
- Hire purchase. You are normally treated as the owner for capital allowances, so you can claim them while paying in instalments. Panels fixed to a building are usually fixtures, so this works through the fixtures rules rather than the hire-purchase rule (HMRC Capital Allowances Manual CA23320). Interest and charges are not part of that claim, so ask your accountant how to treat them.
- Finance lease or operating lease. Capital allowances go to the legal owner, which is the leasing company. HMRC treats the rentals you pay as revenue costs allowable in computing profits, and for an operating lease the timing of the deduction follows your accounts.
- Long funding leases. Some longer leases count as long funding leases, where the lessor loses the right to allowances and the lessee generally gains it. Whether yours is one depends on its terms, so settle that with your accountant before you sign.
Instalments and rentals are fixed by the agreement, not by what the system generates, so the performance risk stays with you.
What commercial solar costs to get started
Funding only makes sense against a properly sized system. Our 100kW solar guide puts a 100 kWp rooftop array at an indicative £75,000–£105,000 installed, about £800–£1,100 per kWp, and our 250kW solar guide puts 250 kWp at £175,000–£240,000. Both give an indicative payback of about four to seven years. These are planning ranges, not quotes: the real figure depends on your roof, your grid connection and how much of the output you use on site.
At those prices a single system sits well inside the AIA's £1 million limit, unless other plant has already used it that year.
Next step: a free feasibility study
The right funding route comes out of your numbers, not a brochure. Book a free feasibility study and we will analyse your half-hourly consumption, model yield with PVGIS, check capacity with your network operator, and compare buying outright, leasing and a PPA with IRR, NPV and payback figures your accountant can test against your tax position.
Projects are delivered by our in-house team and vetted MCS-certified trade partners, and if a site does not stack up we will tell you. Call 03330 384 380 or book your free feasibility study online.
Commercial solar funding: frequently asked questions
Can you claim capital allowances on solar panels? +
Do solar panels qualify for full expensing? +
Has the 50% first-year allowance for solar ended? +
Can a sole trader or farm partnership claim capital allowances on solar panels? +
Can a business reclaim the VAT on solar panels? +
Are there grants for solar panels for businesses in Scotland? +
Who claims the capital allowances under a PPA, lease or hire purchase? +
Can I claim capital allowances if I rent my business premises? +
Related guides
Our reviews on Trustpilot
Free quote in 24 hours.
No high-pressure sales. No commission-driven scripts. Just a no-obligation survey + transparent quote — covering every postcode in Scotland's Central Belt.